Many creditworthy businesses pay double-digit rates to borrow.
For decades, only institutions could earn them. Minimums in the millions. The right connections.
The barrier was never the quality of the lending. It was the size of the cheque.
We built Kasu to end that asymmetry.
Now you can lend into the same kinds of loans: vetted business lending, assessed by specialist Credit Originators, their lending histories in full view.
Take the interest as monthly income, or let it compound weekly. Your capital stays working either way.
Browse vetted lending strategies with clear risk profiles, terms, and track records. Every opportunity has been assessed by institutional credit professionals.
2
Add Funds
Transfer from your bank or digital wallet. Bank transfers settle via US, European (SEPA), Mexican and Brazilian rails today, arriving in your wallet as stablecoins. More regions are being added.
3
Earn interest
Interest accrues and is capitalised at each weekly cycle close, so from week two, your interest is earning interest. Take monthly interest out as income, or leave it compounding.
Institutional-grade credit underwriting helping protect your capital.
Creditworthy borrowers first. Due diligence by institutional credit funds before a lending strategy is offered on Kasu. Technology that reduces lender risk at its source. Then the conventional structure: security and recourse taken by the Credit Originator, and financial and reporting covenants, monitored by institutional senior lenders.
We wrote the page most finance companies won't: the protections explained layer by layer, and an honest walkthrough of what happens when a loan goes wrong. Each Lending Strategy lists its own credit risk structuring before you commit.
Business & personal guarantees + assignment over assets. Exceptions apply
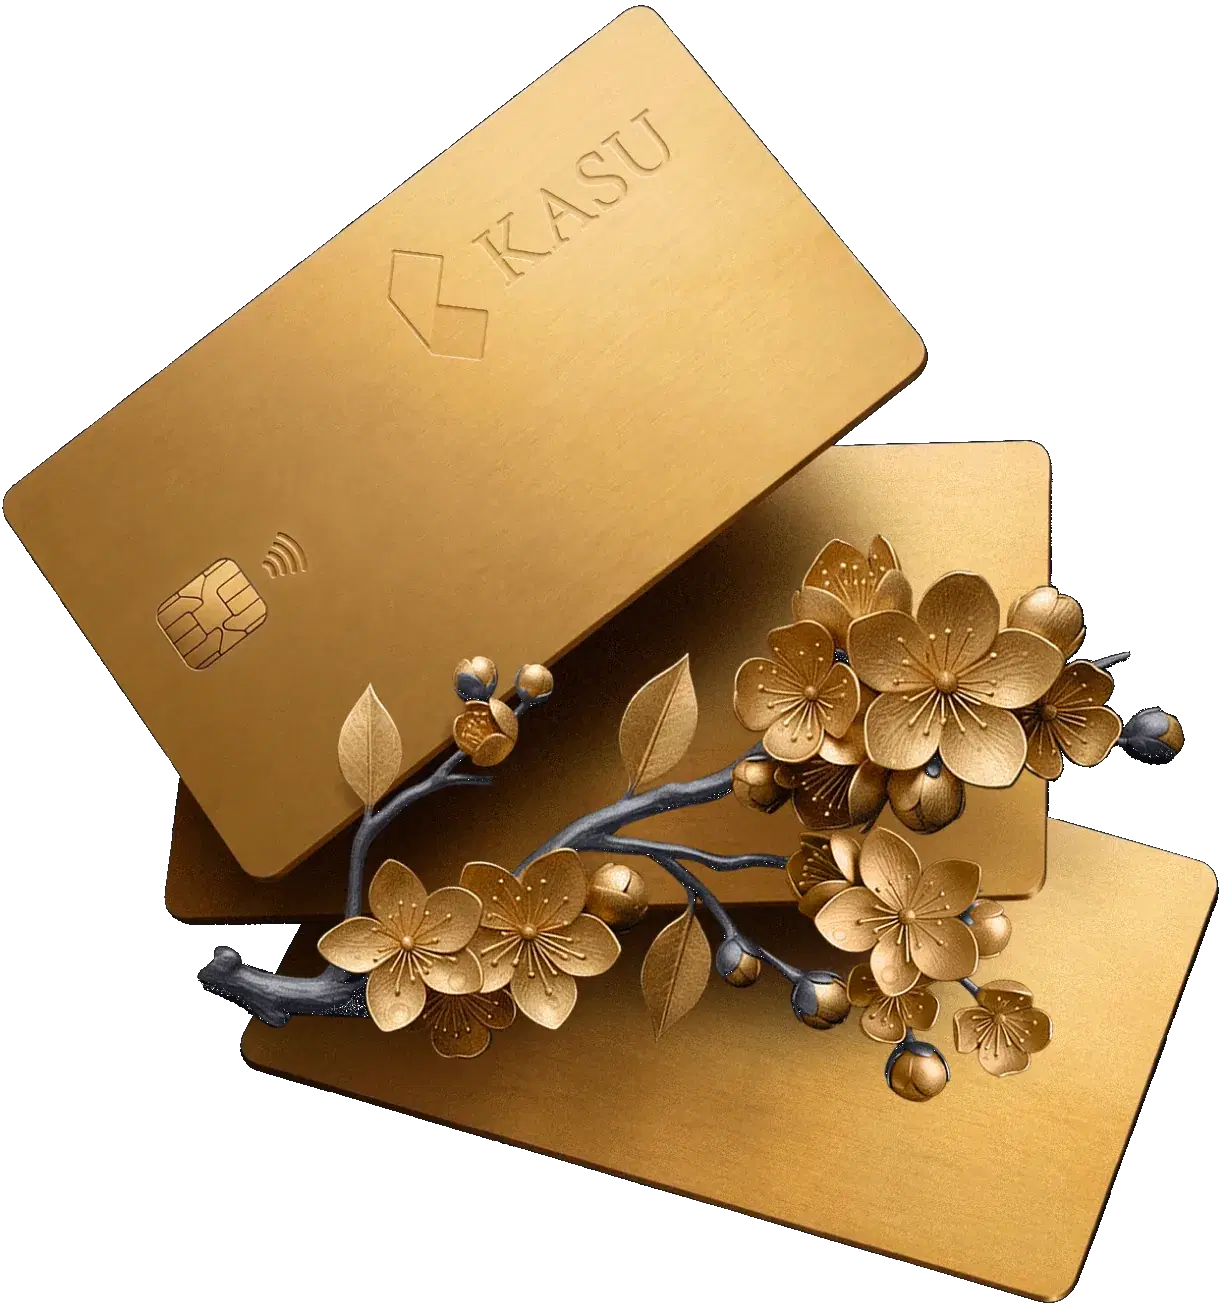
The Kasu Card — coming soon · Lend. Earn. Spend.
Spend the interest. Keep your capital working.
Make your capital work, spend the interest.
The Kasu Card is designed to spend your interest payouts anywhere the card is accepted, while your capital stays lent and working. It draws on interest only, never your lending balance.
Capital remains at risk while lent. Early access by waitlist.
Availability will vary by country. Features described are planned and may change before launch.
Earnings Calculator
The power of weekly compounding.
Kasu compounds interest weekly, and the rate you see already includes it. Same amount, same rate, two ways to take it: draw your interest as monthly income, or leave it compounding.
$5,000$1,000,000
$100,000
8.00%20.00%
14.00% p.a.
The quoted rate, no compounding
14.00% p.a. · interest over horizon $14,000
Compounded weekly, interest paid out monthly
$1,172 monthly income · $14,063 over the horizon
Compounded weekly, left to compound
$15,006
15.01% p.a. effective · Loan Balance $115,006 at end of horizon
The rate we quote is the effective rate: weekly compounding included, nothing added on top, and no fees deducted, because platform fees are paid by the Credit Originator. Your interest starts earning after seven days, not thirty.
Growth of your Loan Balance over the horizon
$120,000
$115,000
$110,000
$105,000
$100,000
Now3mo6mo9mo12mo
Compounded weekly
Quoted rate, no compounding
At the end of 1 year, left compounding
$115,006
Interest earned
$15,006
Effective rate
15.01% p.a.
% gain from compounding
+7.2% · $1,006
This calculator is for illustration only. Projected figures are based on the rate you selected and assume it remains constant and your funds remain lent for the full horizon. The two compounding figures are alternatives: interest is either paid out monthly or left to compound, not both. These are not a promise or forecast of future performance. Withdrawing capital is by request and never guaranteed at any particular time. Past performance is not an indicator of future performance, and Lenders' capital is at risk. Kasu is not a bank and your money is not covered by any government deposit guarantee. Kasu does not provide financial advice.
Track Record
We don't ask you to trust a promise. We show you the numbers.
Apxium's lending track record, through rate cycles and a pandemic, with not one realised loss
9+ yrs
InvoiceMate's lending track record across the UAE and Middle East
3+ yrs
Lender losses to date, across all lending on Kasu
Zero
Figures as at 14 September 2026, from the same source as the app. Past performance is not an indicator of future performance, and Lenders' capital is at risk.
Who Stands Behind Kasu
Backed by institutions that checked first.
Before you lend a dollar, others with far more to lose ran their own due diligence: on the company, and on the lending itself.
*Strategy track records span up to 9 years. Performance history varies by strategy.
United Overseas Bank
Equity Investor
UOB is an equity investor in Kasu and a leading Asian bank with a global network of over 430 branches and offices in 19 markets across Southeast Asia, Asia Pacific, Europe and North America.
XDC Network
Equity Investor
XDC Network is an equity investor in Kasu and an enterprise-grade, blockchain protocol aimed at evolving trade finance through the tokenization of real-world assets and financial instruments.
Cicada Partners
Credit Underwriter · USA
A credit manager with more than $860M underwritten, whose Ripple-backed credit fund lends against InvoiceMate's Payment Financing after months of independent due diligence.
Rixon Capital
Institutional Lender · AUS
An established credit fund holding the entire senior position of Apxium's Australia-based Lending Strategies, committed after extensive due diligence of its own.
Common Questions
What you're probably wondering.
Where does the interest actually come from?
Our Credit Origination Partners are experts in plain, old-fashioned business lending. There is nothing exotic and no financial engineering behind the interest you receive. Underlying borrowers demonstrate strong track records in mature industries, not speculative ventures. Like any healthy business, they need debt to fund operations and growth, and the cash flows from those operations repay the debts, including the interest paid to you.
Is my money insured or guaranteed?
No, and anyone who tells you their double-digit return is guaranteed is lying to you. Kasu is not a bank, and there is no government guarantee behind it; what stands between your capital and a loss is the structure of the lending itself. Every layer, and what happens in a default, is on the Protection page.
Is this crypto?
No. No trading, no speculation, no betting on digital assets. Crypto is a volatile market that sits on top of blockchain: a permanent, shared ledger. The market is not the technology. Blockchain is becoming financial infrastructure, moving more than $33 trillion in the past year, more than Visa and Mastercard combined, and that technology is what makes Kasu possible. Your loans are made in stablecoins: regulated digital forms of currencies like the US dollar and the Australian dollar. Every movement of your funds sits on a permanent record that nobody, including Kasu, can alter.
Can I get my money back at any time?
Often sooner than you might expect, but never on demand. Capital comes back as the book cycles: new funds coming in replace funds going out, and historically lenders have received capital back faster than the strategy timeframes suggested. That is history, not a guarantee. Enter with your strategy’s timeframe in mind, shown clearly in the app before you commit, and treat a fixed term as fixed. If you may need this money at short notice, this is honestly the wrong place for it: compounding only does its real work when the money stays in. Full mechanics on the How it works page.
How is this different from a savings account?
They do different jobs, and both jobs matter. A savings account is government-insured and instantly accessible. Kasu is direct lending to businesses: your money earns the rates businesses actually pay to borrow, carries real risk, and comes back by request as the book cycles, not on demand. The two can sit side by side: the savings account for money you might need tomorrow, Kasu for money you want working harder.